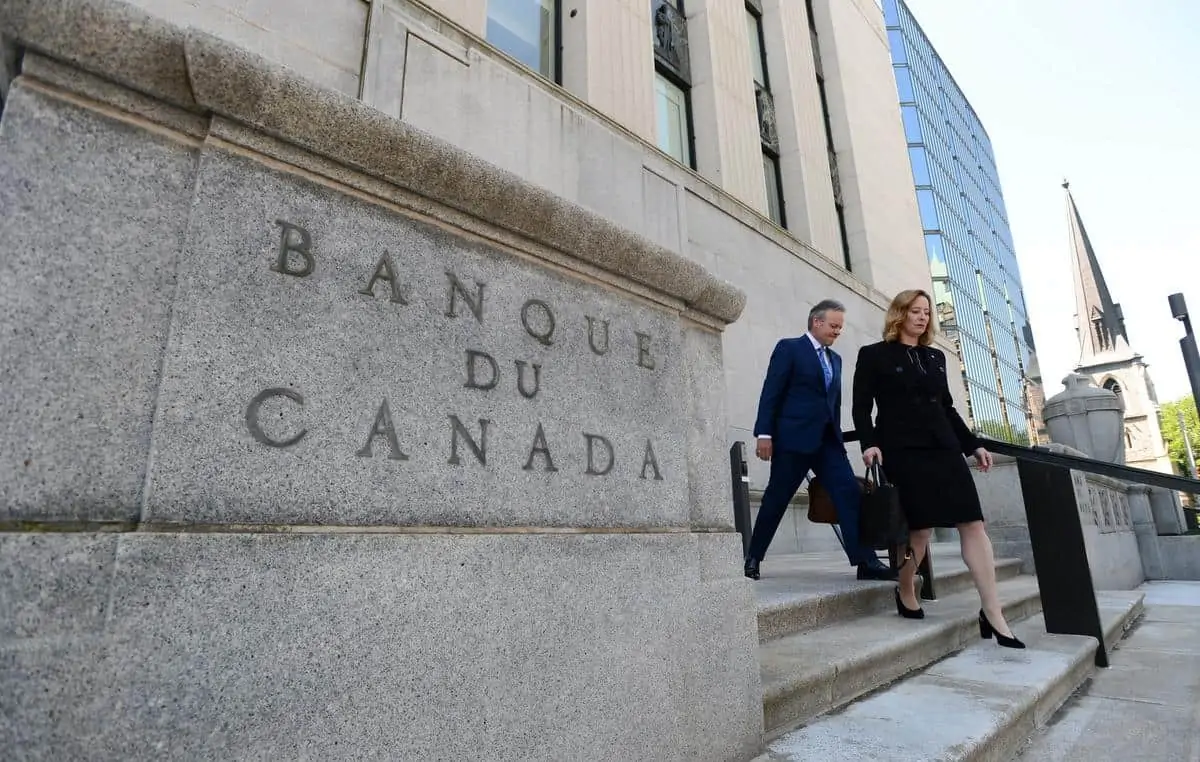
A report recently published by the Bank of Canada outlines several of the benefits and advantages that a digital currency would bring to the development of the country's financial system.
As the United States considers the potential benefits of a central bank digital currency (CBDC) are still unclear, its neighbour Canada is betting on innovation and financial development. CBDCs, or central bank digital currencies, can become an effective instrument for the development of payment systems.
The document published by the Central Bank of Canada, entitled “The Positive Case for a CBDC”, reflects the positive and favorable aspects that the bank has found in the issuance of a digital currency. Innovation, transformation, efficiency, security and reliability are some of the elements that the entity mentions as essential to support the dynamism and development of the digital economy in the country.
For the entity, a digital currency will help solve several of the flaws present in Canada's current financial system; it will also encourage healthy competition and innovation to develop new, highly efficient and reliable financial products and services.
“Overall, competition and innovation are arguments in favor of issuing a CBDC”, reads the document published by the Central Bank. Likewise, the entity argues that the increasing demands of the population for a modern and digital economy is another of the elements that drives the bank in the development of a CBDC.
It may interest you: Governor of the Bank of Canada confirms significant progress for its CBDC
Motivation for issuing a digital currency
Although Canada has been considering issuing a digital currency for some time, the bank noted that the lack of use of cash and competition from cryptoassets or private digital currencies are the main reasons that would motivate the bank to develop and issue a national CBDC.
The Bank of Canada recognizes that with the increasing digitalization of the economy, cash is becoming less relevant as an option for payments, increasing the need for digital money. In addition to this, the entity points out that the need for equity and efficiency in payment systems, which guarantee the well-being of citizens, are also important elements to consider for the development of a digital currency.
A CBDC would help Canada ensure a competitive digital economy by improving the efficiency of current payment systems.
Smart contracts and IoT in the development of the CBDC
The Bank of Canada believes that the integration of innovations such as smart contracts And new technologies such as the Internet of Things (IoT) could also create benefits for citizens by automating transactions and ensuring greater speed and accuracy in business operations.
“A CBDC could support the efficient functioning of new markets that use these technologies, thereby fostering competition and innovation.”he said.
In short, the Bank of Canada believes that a digital currency can offer several advantages over cash, particularly in terms of security and ease of online payments.
Global interest in digital currencies
The Governor of the Bank of Canada, Tiff Mackle, said in October that the entity was working on developing a digital currency with member states of the Group of Seven (G7) to cope with developments in other nations.
Macklem said Canada could issue a digital currency to minimize the risks that the introduction of foreign currencies could cause in its financial system, affecting its monetary sovereignty.
To date, China is one of the most advanced world powers in the development of a digital currency. In fact, the country is just a few months away from officially launching its digital yuan, motivating other nations to move forward on the issue. Meanwhile, in the United States, Federal Reserve (FED) Chairman Jerome Powell stated that the regulator will present a report on the advantages and risks of CBDCs and the cryptocurrencies, in September, although for the moment, it is undecided on the issue of a digital currency for the dollar.
Continue reading: Ukraine calls for a CBDC for cashless retail payments