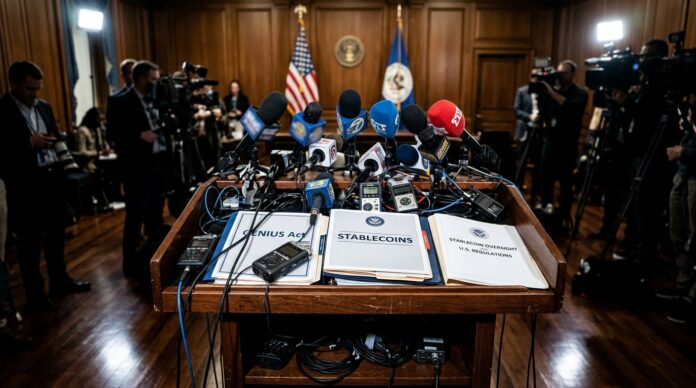
The U.S. Office of the Comptroller of the Currency has finalized the regulatory framework related to the GENIUS Act. This framework establishes strict guidelines on reserves, redemption processes, and operational risk management for issuers of payment stablecoins operating under federal supervision beginning January 18, 2027.
US Treasury Secretary Scott Bessent hailed the regulatory advancement as a watershed moment for the modern financial system. Bessent drew a direct historical parallel between this initiative and the National Currency Act of 1863, enacted during Abraham Lincoln's presidency, which established a federal system for bank fiduciary issuance. He explained that the new regulatory framework seeks to extend that same order and legal backing to the digital currency sector issued by private entities.
A historical parallel with the banking of 1863
The parallel drawn by the Treasury Department places the debate on digital assets at the heart of U.S. monetary sovereignty. In 1863, the fragmentation of currencies issued by local banks generated economic friction and liquidity risks that required a unified solution at the federal level. With the publication of the OCC Final Rules on the GENIUS ActThe regulator aims to standardize the requirements for issuers of dollar-linked tokens operating on a global scale.
Jonathan Gould, the Comptroller of the Currency, emphasized that the provisions offer a clear and practical framework for fostering innovation in payments. The measure aims to stabilize financial markets and ensure that issuers have audited balance sheets and verified technical capacity before trading tokens at retail or institutional levels.
Operating requirements, reserves, and federal oversight
The regulations from the Office of the Comptroller of the Currency detail how the reserves backing each digital unit in circulation must be structured. Issuers will be subject to periodic audits to verify that they maintain a liquid and readily available balance of safe assets, facilitating immediate redemption at par in the event of market stress.
Under these provisions, domestic banks, federal savings associations, and federal branches of foreign entities can fully integrate into the on-chain settlement ecosystem. Additionally, non-bank financial institutions and certain international issuers must obtain formal authorization to continue operating digital payment solutions in the United States.
Impact on digital payments and the 2027 calendar
The institutional timeline allows for a technical adaptation period until January 18, 2027, at which point direct sanctions will begin to be applied against unauthorized entities. Organizations will be required to submit their smart contracts, custody infrastructures, and financial statements for explicit approval by federal regulators.
This transition coincides with the growing adoption of tokens linked to fiat currencies in cross-border transactions and corporate remittances. You can learn more about these digital payment mechanisms by exploring the training materials available at Bit2Me Academy, where the structural differences between public and private blockchains are detailed.
The international context in relation to the MiCA Regulation
The strategy promoted in Washington temporarily converges with the regulatory framework already operational in the European Union through MicaThe EU regulation precisely defines the regime for electronic money tokens and asset-linked tokens, requiring promoters to hold robust safeguards in credit institutions.
Unlike in Europe, where prudential requirements are already enforceable for those offering services with crypto assets, the US model will depend on the interplay between traditional banking supervisors and financial software developers until it reaches full deployment, set for 2027.
FAQ
What does the new regulation require of stablecoin issuers?
Companies must have prior formal approval, maintain verifiable and audited reserves in liquid assets, guarantee exchange rights equivalent to face value, and submit to continuous operational supervision by the Office of the Comptroller of the Currency.
When does this regulation become mandatory?
The regulatory framework derived from the GENIUS Act is scheduled to be fully implemented starting January 18, 2027. Operating without a federal license after that date will result in administrative and legal penalties for the entities involved.
Does this regulation affect entities operating in the European Union?
OCC regulations apply within US jurisdiction to foreign issuers that distribute services there. In the European Union, stablecoin transactions are governed directly and primarily by the mandatory standards set out in the MiCA Regulation.
The establishment of specific federal regulations for stable assets paves the way for a regulated convergence between traditional banking systems and decentralized networks. The requirement for transparent reserves and regular oversight processes redefines the infrastructure of cross-border digital payments.
Investing in cryptoassets is not fully regulated, may not be suitable for retail investors due to high volatility and there is a risk of losing all invested amounts.
Generative artificial intelligence tools were used to create this article.